
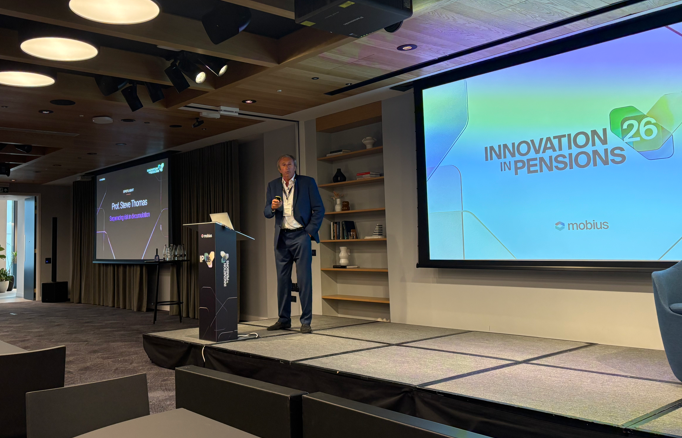

Setting a glide path in retirement is ‘completely useless’ and equities investments should be held in a portfolio for as long as possible, Stephen Thomas, a professor of finance at Bayes Business School, has claimed.
Thomas also proposed a sequence risk ratio which divides the average or expected perfect withdrawal rate by the standard deviation of withdrawal rates across return sequences, providing information beyond the Sharpe ratio in retirement.
“Glide path investing is completely useless, and you should stay in equities to the very end,” says Thomas.
In supporting his case, Thomas pointed to fallout from the 2008 financial crash in the US. According to the SEC, 2010 target date funds lost almost 25 per cent on average in 2008, while individual funds’ losses ranged from roughly 4 per cent to 41 per cent.
At the same event, hosted by investment platform Mobius, Alison Fisher, senior director at Willis Towers Watson, argued that retirement collective defined contribution could materially improved returns for scheme members.
“There are three big problems retirement CDC helps to solve,” says Fisher.
“The first is longevity risk, a big problem for individuals in retirement. The second is adequacy, and getting the most income out of the available assets pot that never has, and finally grounding decumulation solutions in the practicalities of later life and addressing cognitive decline.”
Also at the event, Richard Cliff, a managing director in the private markets royalties team at Partners Group, pitched investment in the firm to Ben Lewis, head of investment proposition at Marsh, Louis Coke, director of private clients at Charles Stanley, and Jo Rickards, trustee director at Prudential Staff Pension Scheme, in a ‘Dragon’s Den’ styled event.
When asked by Corporate Adviser over the controversy surrounding private markets firms owning artist’s back catalogues, exemplified by the long running saga involving Taylor Swift albums being owned by private markets firms Big Machine Label and Shamrock Capital, before being bought back last year, Cliff says: “Taylor Swift willingly sold her catalogue, and then tried to buy it back from people who had bought it from the person to whom she sold the rights in the first place.
“Taylor Swift was not a victim. She was paid very, very well for selling her rights to her publisher and to her record label. An artist, once they have signed their record contract, once they sign their publishing agreement, they are getting paid for having sold an asset to the counterparty. Do they have a gold-given right to buy that (music) back? No.”